Lenders & Brokers Closing $1M+ A Month
Investor Leads
Exclusive.
Under Your Brand.
Non-QM, hard money, and private lending. 94.4% investment property across 5,185 leads.
Watch before you book
One-time build. No retainer.
You own the CPL. Scale up or down.
15 min · Google Meet · Direct with Ryan
Comp under 2.0 points? Not a fit yet.
Ryan RobertsFounder
Client Averages
14x
Return on Ad Spend
Client average, portfolio-wide
$569K
Avg Closed Loan Value
Per funded transaction
7
Funded Units / LO / Mo
Average across active clients
$1,200
Cost per funded deal
Portfolio-wide
Client averages across active accounts, portfolio-wide. Not typical. Results vary.
Measured, Not Claimed
Lead Quality
Is Measurable.
Most lead gen providers can't show you this because they don't track it. Every lead comes from a first-party audience of 228,000 real estate investors. Credit and liquidity answered before the first call. A property already selected. Not scraped, not shared, not skip-traced.
Book-wide investor lending data
5,185 leads
13 client accounts
April 2025 to July 2026
Data as of July 28, 2026
First-party data. One-to-one consent. TCPA, CCPA, and GLBA-aware capture.
49.4%
Purchase
26.5%
Cash-Out
24.1%
Refi
Credit and liquidity are self-reported on the form. The box runs in the ad. It filters. It does not guarantee.
Want to see whether this data maps to your product box?
The Mechanism
How It
Actually Works.
01
First-Party Targeting
228,000 real estate investors. Credit and liquidity answered before the first call. A property already selected. Not a scraped list. Not a shared database. Not skip-traced data from a vendor. Every lead enters your pipeline from this audience, under your brand, in your market, against your product box.
02
First Click Deterrence
Your lending criteria go directly in the ad. As a deterrent. Rate. LTV. Credit minimum. Loan amount. The wrong borrower reads it and keeps scrolling. The right borrower clicks. Across 5,185 leads, 82.0% reported 660+ credit. Filtration, not volume.
03
You Own the Infrastructure
Your ad account. Your pixels. Your data. Your consent records. No black box. No dashboard that disappears when you leave. The system compounds after we stop working together. That's the difference between building a business and renting a dependency.
Ready to pressure test the mechanism against your market?
Ad Examples
Creative That
Filters Before
The Click.
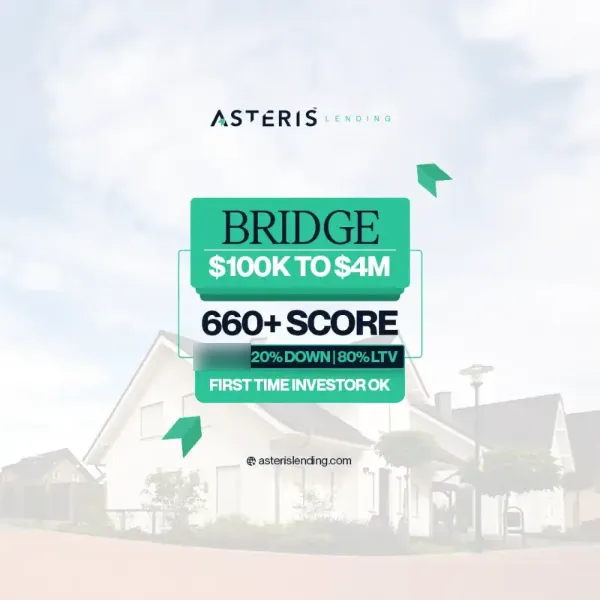
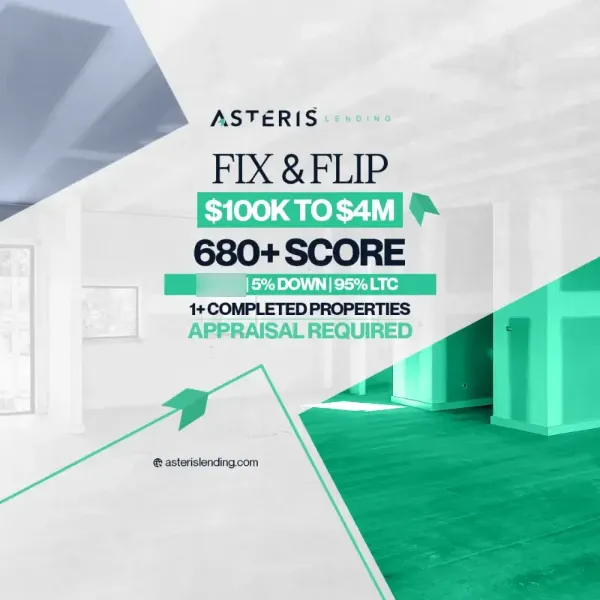
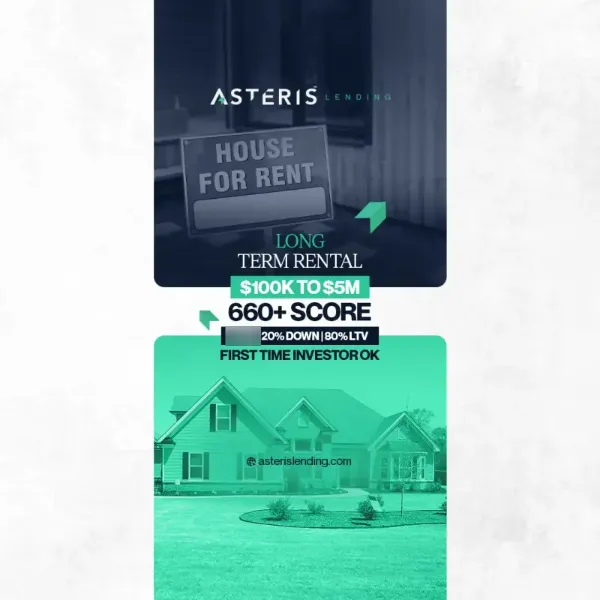
Real campaign creative from client accounts: DSCR, bridge, fix and flip, hard money, short-term rental, ground-up construction, investor refinance, multi-family, and long-term rental. The box prints in the ad, so non-investors and first-timers screen themselves out before the click.

 Asteris Lending
Bridge

 Asteris Lending
Fix & Flip
 Asteris Lending
Long-Term Rental
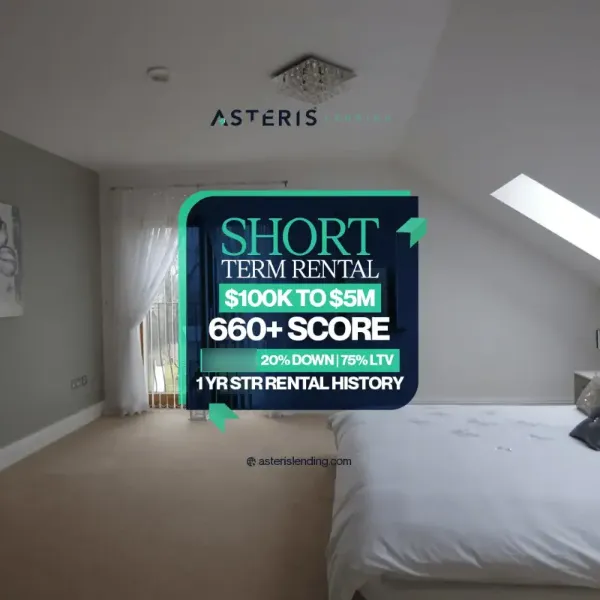 Asteris Lending
Short-Term Rental
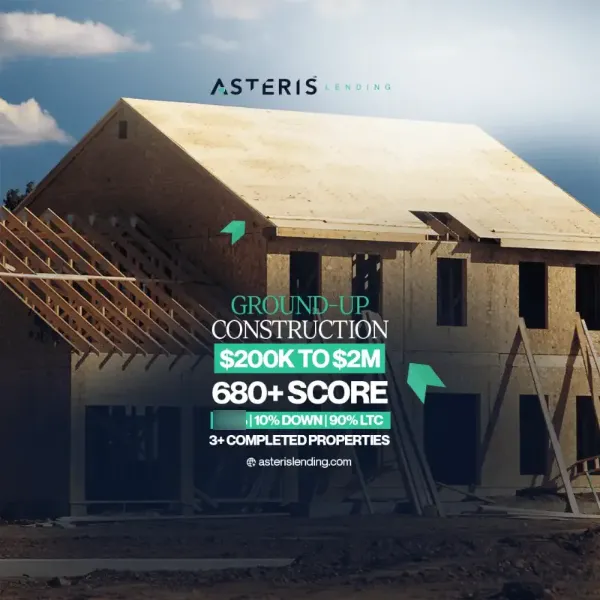 Asteris Lending
Ground-Up Construction
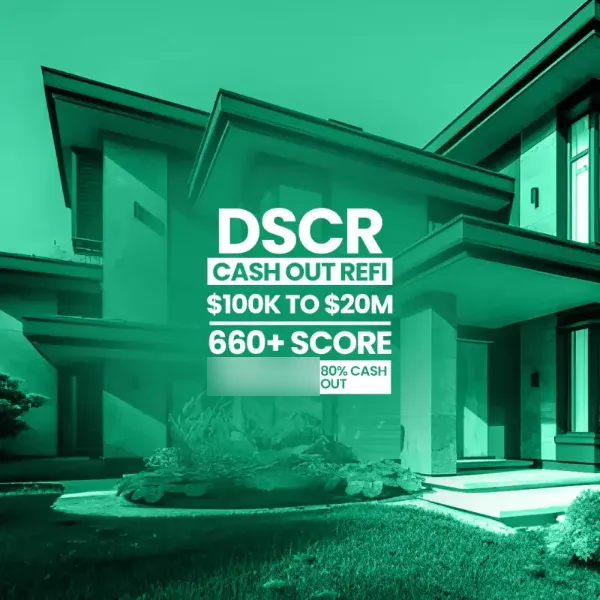 Investor Loans
Cash-Out Refi
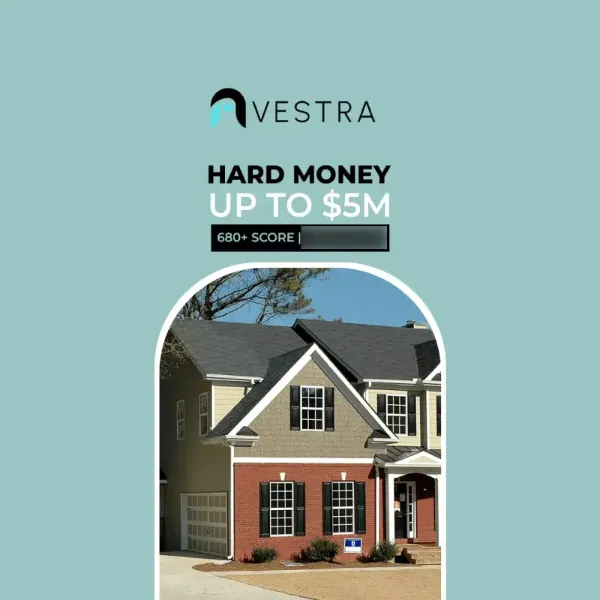 Vestra Funding
Hard Money
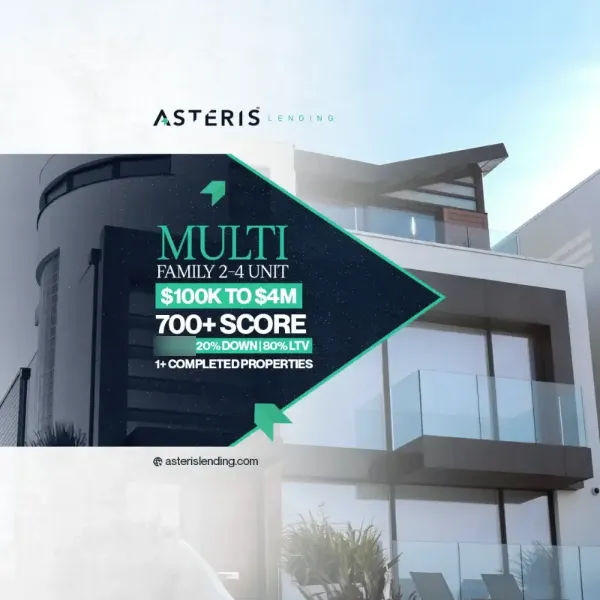 Asteris Lending
Multi-Family
ROAS Calc
See The
Economics.
Use the benchmark numbers below or plug in your own funnel. The model shows what each ad dollar could produce across leads, applications, funded loans, revenue, and net after spend. It is a model of your inputs, not a promise.
Inputs
Upper Funnel
$
Total leads generated from paid acquisition.
%
Percent of leads you successfully reach.
Mid Funnel
%
Percent of contacts who complete a loan application.
Bottom Funnel
%
$
bps
Basis points earned per funded loan. 100 bps = 1%.
Return On Ad Spend
14.15x
for every $1 spent on ads
Monthly Revenue
$120,267
Net After Spend
$111,767
Cost Per Funded Loan
$1,227
Closed Loans / Mo
7
Leads Generated
154
Cost per lead: $55
Contacts Established
92
Contact rate applied.
Loan Applications
14
Cost per app: $613
Closed Loans
7
Lead-to-close rate: 4.50%
Total Lending Volume
$3,943,170
Projected monthly production.
Cost Per Lead
$55
Cost Per Application
$613
Cost Per Funded Loan
$1,227
Lead-to-Close Rate
4.50%
What Scaling Looks Like
| Monthly Spend | Closed Loans | Monthly Revenue | Monthly Net | ROAS |
|---|---|---|---|---|
| $4,250/mo | 3 | $60,133 | $55,883 | 14.15x |
| $6,375/mo | 5 | $90,200 | $83,825 | 14.15x |
| $8,500/mo | 7 | $120,267 | $111,767 | 14.15x |
| $12,750/mo | 10 | $180,400 | $167,650 | 14.15x |
| $17,000/mo | 14 | $240,533 | $223,533 | 14.15x |
| $25,500/mo | 21 | $360,800 | $335,300 | 14.15x |
| $42,500/mo | 35 | $601,333 | $558,833 | 14.15x |
| $63,750/mo | 52 | $902,000 | $838,250 | 14.15x |
| $85,000/mo | 69 | $1,202,667 | $1,117,667 | 14.15x |
Straight-line model: cost per lead is held constant, so ROAS is the same on every row. Real accounts rarely scale that cleanly.
Ready To Pressure Test The Numbers?
Bring these numbers to the call. I'll run them against live lead data for your product. One-time implementation fee, no mandatory retainer, optional ongoing management tied to funded production.
Get a Custom ROAS Projection
Hard Qualification
This Doesn't
Work For
Everyone.
About 1 in 20 qualification calls booked turns into a client. The other 19 are either not a fit or I don't take them on.
More leads into a broken system produce bigger losses faster. I've seen exactly how this fails and I don't build programs that fail.
If I can't create value for you, I'll tell you on the call.
Not closing $1M+/month in funded volume yet
Comp structure under 2.0 points
Can't deploy $8,500+ a month in ad spend
No underwriting infrastructure or follow-up process
Last-ditch effort to rescue a struggling pipeline
Client References
Operator
Feedback.
The best leads I have ever worked. Consistent quality, real investors, and a system that actually works. I am closing over $4M a month now and nothing else has come close.
Shaun L.
Loan Officer
I have tried nearly every lead source in non-QM. Ryan's system is the only one where I can actually predict my pipeline. The borrower quality is completely different.
Courtney N.
Lending Executive
We scaled from roughly $2M to $6M a month in funded volume in under 90 days. The infrastructure is clean, the data is real, and we own everything.
Daniel S.
Branch Manager
The first click deterrence approach changed how I think about lead generation. We cut unqualified volume hard and our cost per funded deal improved.
Chase Z.
Senior Loan Officer
What separates Ryan from other shops is that he thinks in unit economics, not vanity metrics. He told me what needed to be fixed before scale and he was right.
Luis P.
Private Lender
The data quality on these leads is the best I have seen. Credit, liquidity, and property intent are far stronger than the recycled lead sources we were buying before.
Anthony L.
Lender
We did not need more lead count. We needed better lead filtration and better economics. That is exactly what this delivered.
Christian G.
Loan Officer
The difference is ownership. Ad account, pixels, data, consent records, capture systems, all of it lives with us. We are not renting a black box anymore.
Rafik I.
Mortgage Executive
Ryan was direct from day one. He told us where our process was weak, helped tighten the funnel, and the lead quality held up as volume increased.
Didio M.
Sales Manager
This is one of the only programs I have seen where the economics make sense all the way through to funded deals. It is built for operators, not browsers.
Tyler H.
Non-QM Originator
We were spending money on noise before. Now the inquiries are aligned with our product box and our team is spending time with people who can actually close.
Trevor C.
Lending Partner
The thing I respect most is that Ryan will tell you when you are not ready. That honesty saved us from scaling the wrong system and helped us fix the right one.
Jesse B.
Private Capital Advisor
Individual results. Not typical of every client.
I'll give you direct phone numbers. Call them before you make a decision.
Client Videos
Watch The
Receipts.
Find Out If You Qualify
Book
The Call.
I'll walk through the actual lead data, introduce you to real clients, and tell you clearly whether this makes sense for your program. The structure is simple: a one-time implementation fee, no mandatory monthly retainer, and optional ongoing management tied to funded production. When you win, I win.
15 min · Google Meet · Direct with Ryan
Every month you spend on recycled leads is a month you're funding someone else's arbitrage.
Frequently Asked Questions
FAQ
Lenders and brokers already closing $1M to $3M or more per month in funded non-QM, hard money, or private lending volume, earning 2.0 points or better per loan, and ready to deploy $8,500 or more a month in ad spend. You need underwriting infrastructure in place and a loan officer who actually follows up. If those boxes are checked, we can talk.
Anyone treating this as a last-ditch effort to save a pipeline that's already broken. Anyone who can't deploy the minimum budget. Anyone whose comp is under 2.0 points per loan, because the math won't support the acquisition cost. And anyone who doesn't have a contact sequence and operational follow-up in place. More leads into a broken system just produce bigger losses faster.
Most lead sources run a shared consent model. The same borrower is sold to several lenders at once, and you end up competing for someone who didn't know their information was being resold. My system is built on first-party data and one-to-one consent. Each lead goes to you alone, under your brand, from a first-party audience of 228,000 real estate investors.
The full non-QM, hard money, and private lending stack. DSCR, both long-term and short-term rental. Bridge loans. Fix and flip. Ground-up construction. Hard money. Investor refi. Bank statement. Asset utilization. 1099. Interest only. Multi-family 2 to 8 unit. Foreign national. Closed-end seconds. Commercial. If you're lending to real estate investors, there's a campaign structure for it.
Yes. And this is one of the most underserved and overlooked segments in the entire lending ad space. Almost nobody is running serious paid acquisition for wholesale and TPO channels in non-QM and private lending. The brokers and correspondent partners are out there, they're active, and they're being ignored by every major lead gen provider. I build dedicated campaigns targeting broker networks, TPO channels, and correspondent relationships, with the same first-party data infrastructure and first click deterrence approach used on the retail side. If you have a wholesale or TPO division and you're not running paid acquisition for it, you are leaving a significant amount of production on the table.
Across 5,185 leads from 13 client accounts, April 2025 to July 2026: 82.0% reported 660+ credit, 94.4% were investment property, 58.5% requested $250K or more, and 46.0% reported $50K or more in liquidity. Intent mix: 49.4% purchase, 26.5% cash-out, 24.1% refinance. Every lead includes a credit range, a liquidity range, the full property address, and contact information. Credit and liquidity are self-reported. Data as of July 28, 2026. I'll pull the lead-level data on the call.
The structure is a one-time implementation fee to build the campaigns, Google Apps Script lead capture systems, and first-party targeting. There is no mandatory monthly retainer. Ongoing management is optional and can be structured around performance, relationship stewardship, and funded production. You own the ad account, data, pixels, consent records, and capture systems from day one.
Across active clients the average is 14x. At $8,500 a month in spend, that is 7 funded units per loan officer per month at a $569K average closed loan and 3.05 points (305 bps) in comp, or about $121K in monthly revenue per loan officer. These are client averages, portfolio-wide, not a promise, and results vary. I'll show you the account data on the call.
Leads start arriving once the campaigns go live. From there, funded production depends on your ability to collect loan applications, process them, and move toward closing. Depending on the product, that cycle runs 20 to 30 days. You will often issue pre-qualification letters well before a deal closes. Those are lines in the water. The pipeline builds fast. The closings follow your operations, not the traffic.
Scaling is a math problem, not a confidence problem. You need three numbers locked in before you increase budget: cost per lead, cost per loan application, and cost per funded deal. Once those are stable and within par (portfolio-wide, about $55 per lead, about $680 per application, and about $1,200 per funded deal), scaling becomes a matter of sustaining operations while removing the emotional resistance to higher ad spend. Most high-performing individual loan officers top out around $15,000 a month in spend. Most lenders running team operations land in the $30,000 to $60,000 a month range. The ceiling is determined by your operational capacity, not the platform.
Yes. That's a non-negotiable part of how I build. Your ad account, your pixels, your first-party data, your consent records, your capture systems. Nothing lives in a proprietary platform that disappears when we stop working together. The infrastructure compounds after we're done. That's the point.
Most aggregators run shared consent: one form fill, several buyers. A lot of them push the compliance risk downstream to you through indemnification clauses in their contracts. I build on one-to-one consent instead. Every lead consents to one lender: you. The lenders winning right now stopped renting someone else's audience and started building their own. That's what this system does.
I run a short qualification check first: your production history, product focus, comp structure, and how your operations run. If there's clear misalignment, I'll tell you directly and explain why. If you're a fit, we walk through the actual lead data in a spreadsheet, review how the campaigns are structured, and talk through the economics for your product and market. At the end I introduce you to references: real clients who will give you direct feedback. Then you decide.
Yes. After the qualifying call confirms mutual fit, I make direct introductions. Names, emails, and phone numbers. These are active lenders and loan officers who will tell you exactly what working with me is like, including what didn't go perfectly. I have no interest in closing clients who aren't a genuine fit for the program.
Because I've seen exactly how this fails when the wrong operator is in the seat. Weak contact rates, no follow-up discipline, comp that can't support acquisition cost, ops that break under volume. Scaling traffic into that environment just produces bigger, faster losses. I take on a small number of clients at a time and I stay close to every account. That only works if the clients qualify.
Because this is a statistics game. Every dollar buys exposure, and exposure turns into loans through a chain: impressions, clicks, form fills, conversations, applications, funded deals. Each step converts at a rate you don't control. Below $8,500 a month there isn't enough volume moving through that chain to produce reliable data. You end up deciding on thin samples, cutting campaigns that would have worked and scaling ones that won't. Then the math breaks and the leads get the blame. The $8,500 floor is not arbitrary. It is the point where you have enough volume to measure what's happening and decide where to scale. Below it, you are not running a demand generation program. You are running an experiment with your own money.
Seen enough? Book the call.